Container rates moved higher again this week as carriers continued adjusting capacity across major East-West trade lanes, while a potential labor disruption at the Ports of Los Angeles and Long Beach emerged as an immediate operational concern ahead of November 1.
Blank sailings are increasing sharply on Asia-Europe services as carriers work to manage capacity, while Trans-Pacific capacity is beginning to improve. Air cargo volumes also rebounded following Golden Week, and USTR has formally proposed extending the suspension of its Section 301 maritime measures targeting China's maritime, logistics and shipbuilding sectors through January 9, 2027.
MARKET SUMMARY OVERVIEW
Drewry's World Container Index rose 2% for the week of October 22, marking its second consecutive weekly increase and the highest level in 15 weeks.
Shanghai-to-Los Angeles increased 2%, while Shanghai-to-New York rose 1%. Asia-Europe recorded stronger gains, with Shanghai-to-Rotterdam up 3% and Shanghai-to-Genoa up 5%.
Drewry expects Trans-Pacific rates to remain broadly stable in the near term, while Asia-Europe pricing could continue higher as carriers reduce capacity. Xeneta's latest data shows a similar divergence, with stronger upward movement into Europe while Trans-Pacific spot rates have largely leveled off.
LOS ANGELES AND LONG BEACH: WATCHMEN'S STRIKE COULD BEGIN NOVEMBER 1
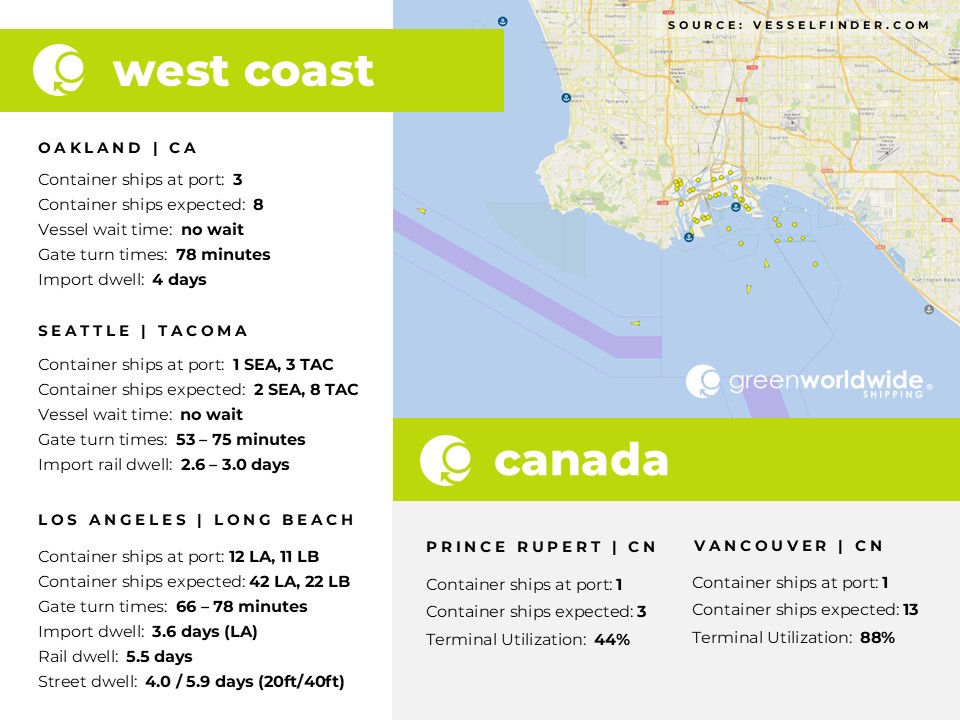
International Longshore and Warehouse Union Local 26, representing approximately 250 security watchmen at marine terminals in Los Angeles and Long Beach, has authorized a strike that could begin as early as 5:00 p.m. Pacific on Sunday, November 1.
The latest extension of the union's contract with the Pacific Maritime Association expires that day. The previous agreement expired in July 2025, and negotiations have continued with federal mediators.
PMA says Local 26 watchmen work at terminals handling approximately 85% of cargo at the Port of Long Beach and 33% at the Port of Los Angeles. PMA has also said it expects other ILWU members to honor potential picket lines, which could affect vessel, yard and gate operations at impacted terminals.
No strike has been confirmed, and negotiations remain ongoing. Shippers with cargo moving through San Pedro Bay in early November should closely monitor terminal operations and confirm pickup, delivery and vessel schedules.
BLANK SAILINGS INCREASE ON ASIA-EUROPE SERVICES
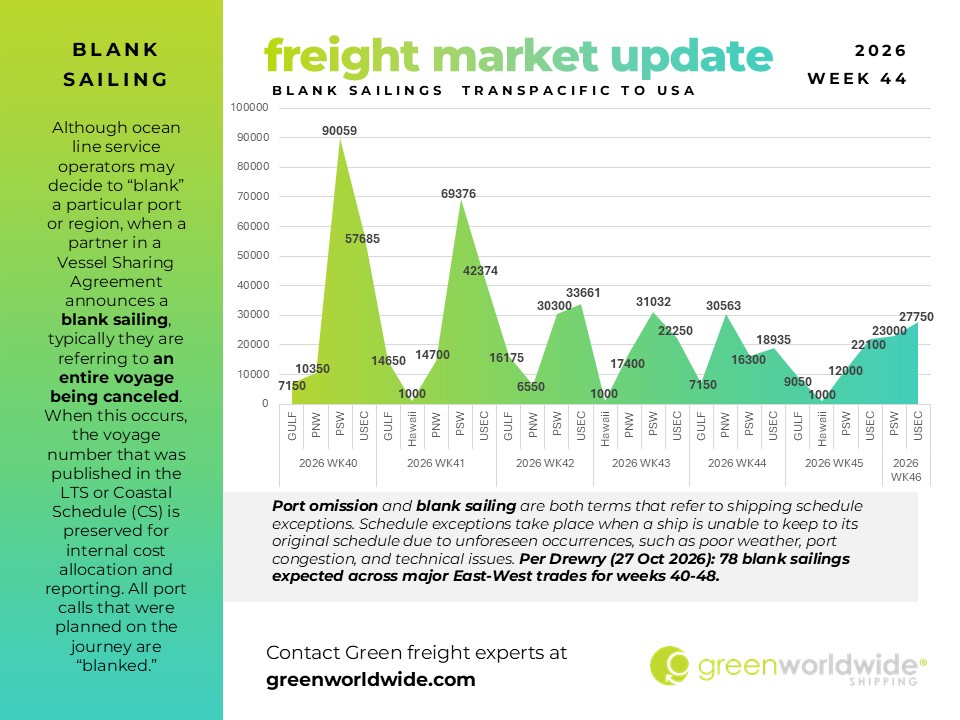
Drewry's Cancelled Sailings Tracker lists 56 blank sailings out of 714 scheduled voyages across Weeks 44 through 48, representing an 8% cancellation rate. Approximately 92% of scheduled sailings are still expected to operate.
Asia-North Europe and Mediterranean services account for 54% of announced cancellations, followed by Trans-Pacific eastbound services at 32% and the Transatlantic at 14%.
For the upcoming week, Drewry reports eight Asia-Europe blank sailings, up from two during the current week. Trans-Pacific blank sailings are expected to fall from six to two.
The increase in Asia-Europe cancellations points to tighter effective capacity as carriers continue managing supply to support rates. Shippers moving cargo into Europe should confirm November sailings and available space, while Trans-Pacific importers should continue monitoring carrier schedules and all-in pricing.
PORT CONGESTION EASES AT SHANGHAI
Congestion at key Asian ports has begun to ease, with Drewry reporting a significant improvement at Shanghai.
Average vessel waiting times at Shanghai fell from approximately 97 hours in Week 38 to 38 hours by Week 42 as recent disruption cleared.
The improvement should support better schedule reliability, but carrier network adjustments and blank sailings continue to affect individual services. Importers should continue confirming vessel assignments and cutoffs rather than assuming schedules have fully normalized.
AIR CARGO REBOUNDS AS Q4 DEMAND BUILDS
Global air cargo activity rebounded following China's Golden Week holiday period.
WorldACD reported global chargeable weight increasing 2% week-over-week during October 12-18, while average rates increased 4% and capacity rose 2%.
Asia Pacific was the only origin region to record volume growth, increasing 9% week-over-week. Export volumes from Asia Pacific to Europe rose 13%, while volumes to the United States increased 10%.
The rebound comes as factories resume production and fourth quarter demand builds. Shippers moving high value or time sensitive freight from Asia should continue planning bookings early as available capacity and pricing respond to peak season demand.
USTR PROPOSES EXTENDING MARITIME MEASURE SUSPENSION THROUGH JANUARY 9
The Office of the U.S. Trade Representative has formally proposed extending the suspension of its Section 301 action addressing China's maritime, logistics and shipbuilding sectors for an additional two months.
Under the proposal, the current suspension would continue from November 10, 2026 through January 9, 2027. During that period, affected parties would not accrue liability for or pay the maritime transport service fees covered by the suspended action.
Written comments are due by 5:00 p.m. Eastern on Friday, October 30.
The proposal is an important procedural step, but the extension is not yet final. The current suspension remains in effect through November 9 unless USTR formally modifies the action.
Importers and carriers should continue monitoring USTR announcements ahead of the November deadline.
Stay up-to-date on freight news with Green’s Weekly Freight Market Update by following us on LinkedIn. For continuous updates, make sure to check out our website at greenworldwide.com.